

The Scheduled Castes and Scheduled Tribes (Prevention of Atrocities) Act was enacted for a compelling and necessary purpose: to protect vulnerable communities from genuine discrimination, humiliation, violence, wrongful dispossession, and atrocities. There can be no argument against such protection. But precisely because the law is powerful, its provisions cannot be allowed to become a convenient instrument for frustrating legitimate legal and commercial processes.
The recent Axis Bank episode raises precisely that uncomfortable question.
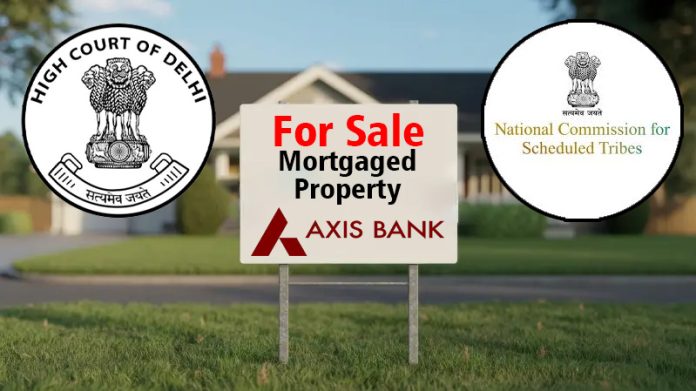
According to the proceedings before the Delhi High Court, Axis Bank had sanctioned a credit facility of about ₹16.69 crore to Sundev Appliances Ltd in 2013 against a mortgaged property in Vasai, Maharashtra. After the borrower failed to repay, the account was classified as an NPA in October 2017. The bank subsequently invoked its statutory rights under the SARFAESI Act to enforce its security interest.
What followed is extraordinary enough to merit serious public scrutiny.
Amid a subsequent dispute over ownership of the mortgaged property, a representation was made before the National Commission for Scheduled Tribes alleging violations under Sections 3(1)(f) and 3(1)(g) of the SC/ST Act. The NCST then summoned Axis Bank’s Managing Director and CEO to appear personally.
The Delhi High Court was not impressed.
Justice Sachin Datta, in an October 16, 2025 order, made a prima facie observation that the provisions invoked could not be used to prevent the exercise of mortgage or security rights by the bank. The Court also stayed the proceedings before the Commission, observing that the summons requiring the bank’s MD and CEO to appear personally were without jurisdiction and that no rationale had been recorded for demanding their personal appearance.
This is where the larger issue begins.
Can a statutory protection intended to prevent caste-based atrocities be stretched into a mechanism for obstructing a bank from recovering a legitimate debt or enforcing a lawful mortgage? Surely not.
A loan does not become a social-justice issue merely because the borrower happens to belong to an SC or ST community. Nor does a banker become an offender merely because his professional responsibility requires him to recover public or private money. Caste cannot become a shield against contractual obligations, just as caste can never be a justification for discrimination.
There is an equally important dimension here. Bank officials are not private debt collectors acting on personal whims. They operate within institutional frameworks, regulatory requirements, and statutory recovery mechanisms. If they fail to recover legitimate dues, they may themselves face questions from their employers, auditors, regulators and shareholders.
Imagine the chilling effect if every routine recovery action could be transformed into an allegation under a stringent criminal statute. Would a branch manager have the confidence to initiate recovery? Would a recovery officer enforce a mortgage? Would senior executives be willing to take difficult decisions if they could be summoned personally before statutory commissions on the basis of allegations arising from ordinary banking activity?
That would not protect social justice. It would undermine institutional accountability.
At the same time, there must be no misunderstanding: genuine caste-based atrocities must be dealt with firmly and without fear or favour. The answer to misuse of the law cannot be dilution of protection for genuine victims. The answer is rigorous scrutiny of facts and application of the law exactly as Parliament intended.
The judiciary, police and statutory commissions therefore have an enormous responsibility. They must distinguish between an actual atrocity and a commercial dispute dressed up as one.
The Axis Bank case is not merely about one bank, one borrower or ₹16.69 crore. It is about whether Bharat’s legal architecture will protect both social justice and the rule of law.
The SC/ST Act must remain a shield for the genuinely oppressed—not become a sword against those performing legitimate professional duties.
And when allegations are made, the first question should always be simple: Where is the atrocity?


Lakshman Rao.
Strong Defence of the Rule of Law
The editorial “Loan, Not Caste” is a timely and thought-provoking piece that addresses a sensitive issue with commendable clarity and balance. Its central argument—that laws created to protect genuinely oppressed communities must not be misused to obstruct legitimate banking, commercial, or legal processes—is both relevant and important.
The editor deserves appreciation for placing the Axis Bank episode within the larger framework of institutional accountability, social justice, and the rule of law. The article does not question the need for strong protection against caste-based atrocities; instead, it rightly emphasizes that genuine social justice is strengthened when legal provisions are applied carefully, factually, and without allowing them to become instruments in unrelated commercial disputes.
Particularly significant is the article’s reminder that caste cannot be a shield against lawful contractual obligations, just as caste can never justify discrimination. This balanced formulation gives the piece its intellectual strength.
Overall, Loan, Not Caste is a courageous and relevant editorial intervention. It encourages readers to look beyond labels and allegations and ask the fundamental legal question: Does the evidence establish an actual atrocity, or is a legitimate commercial dispute being presented as one? That insistence on facts, due process, and institutional integrity makes the article a valuable contribution to responsible journalism.